Risk and resilience in global grain trade
Despite conflict, climate shocks, and shifting trade dynamics, the global grain market is proving resilient in 2025, with Ukraine sustaining exports, China reducing imports, and maritime routes coming under pressure.
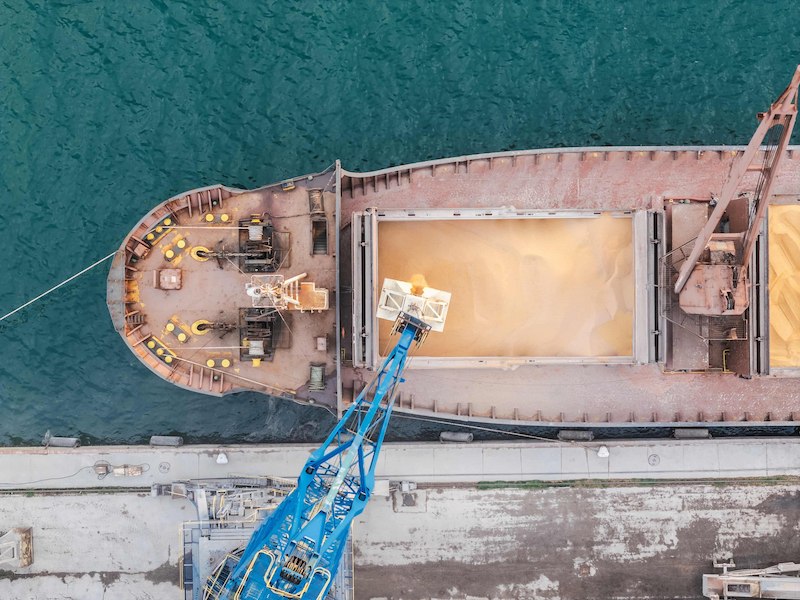
Global grain markets stand at a crossroads. A relative calm in 2024 gave way to cautious hope, but geopolitical tensions, particularly the Ukraine-Russia peace talks and global macroeconomic volatility, continue to cast long shadows over the future of grain trade and the vital shipping routes that sustain it.
Despite Russia’s missile strike on Odessa in March, Ukraine’s exports have continued through a unilateral humanitarian corridor, bypassing the defunct Black Sea Grain Initiative. Peter Clubb, Market Analyst, International Grains Council (IGC), told ICS Leadership Insights, “dispatches of grains and oilseeds from Ukraine have progressed at a healthy rate,” though at higher logistical costs. Russia, meanwhile, has maintained strong volumes, though reduced crop yields for 2024/25 could curb output.
Clubb added that “security challenges in the Red Sea… have perhaps had a bigger impact,” with ships rerouted around the Cape of Good Hope, extending voyage time and costs.
Beyond conflict, other disruptions are straining the system. Deepanshi Puggalok, Research Analyst at Drewry Maritime Research, told ICS Leadership Insights: “The grain market showed resilience in 2024, growing by 2% despite facing challenges like unpredictable weather, logistical delays from low water levels in the Panama Canal, and political instability in the Red Sea. However, overall stability in global production helped mitigate these issues.” She said the outlook for 2025 is less optimistic, as “escalating trade tensions and retaliatory tariffs from major grain-producing countries disrupt global trade.”
The food security challenge
The World Food Programme (WFP) has warned of worsening food insecurity. In 2024, 343 million people faced acute shortages – more than double pre-pandemic levels. Funding cuts and political instability are reshaping where grain is needed and how it is delivered.
Asia and Africa continue to drive global grain demand, fuelled by rising populations and changing diets. Clubb noted that while economic headwinds may slow growth slightly, overall demand remains strong. Brazil and Australia have strengthened their roles as major exporters. Brazil’s maize and soybean exports to Asia have stabilised markets, while Australia is pivoting toward emerging demand in sub-Saharan Africa amid China’s retreat from the market.
China, once a major importer, is now pushing for self-sufficiency. “Corn imports fell nearly 50% in 2024,” Puggalok said. Brazil overtook the US as China’s primary corn supplier, and the US’s share of global grain exports could fall from 22% in 2024 to around 12%. China’s wheat production is also set to reach a record 140 million tonnes, further reducing its need for imports.
Meanwhile, EU reliance on Ukrainian corn remains strong, though Spain has shifted some imports to US corn. In Latin America, Colombia’s corn imports are forecast to hit a record high in 2025, driven by lower domestic production and higher feed demand.
Shipping’s crucial role
Shipping remains the backbone of the global grain supply chain. “The very nature of the global food system… is to move foodstuffs from areas of surplus to areas of deficit,” Clubb said. Dry bulk carriers, in particular, are essential. Yet, the maritime sector faces growing challenges, including Suez Canal security threats, climate-induced low water levels at the Panama Canal, and inland bottlenecks from the US Midwest to the Rhine River in Germany.
The political impact of policies being imposed by the US Administration are also raising concerns for global grain trade. The Office of the US Trade Representative (USTR) has proposed remedies in Section 301 following investigations into China’s maritime logistics and shipbuilding that are designed to address “unfair foreign practices affecting US commerce”. This includes a proposed service fee on Chinese maritime transport operators and operators with Chinese-built vessels in their fleets.
During a public hearing in March of the Section 301 investigation, the American Farm Bureau Federation noted that bulk agricultural exports, especially grains and
oilseeds, are vulnerable to USTR actions. The National Grain & Feed Association (NGFA) response submitted to the USTR on 24 March opposed the USTR’s initial proposals, noting that “while well-intentioned, the proposals threatened to impose significant costs on US grain and oilseed exporters and erode America’s competitiveness in the international market.”
The original proposed penalties included fines of up to US$1.5 million for each Chinese-made ship that enters a US port, which NGFA president and CEO Mike Seyfert explained “would effectively eliminate half of the global bulk fleet that we need to export almost one third of grains and oilseeds that are produced in America”. While the revised penalties have been scaled back from the originally proposed levels, they are still excessive and carry detrimental consequences for the U.S.’ grain exports.
Soybean markets are also feeling the strain. “The global soybean trade is expected to fall in 2025 due to the trade war, though recovery is anticipated,” Puggalok said. China’s soybean demand remains strong. Amid concerns over tariffs and a delayed Brazilian harvest, China temporarily increased US imports, but by mid-2025, Brazilian soybeans are expected to surge again.
This realignment is expected to “accelerate Panamax rates,” Puggalok said, with tariffs hitting US exporters hardest. “The US exports almost half its soybeans to China, but China sources only about a quarter of its soybeans from the US.”
Related content
Shipping Industry Flag State Performance Table 2025/2026

Introducing the Deck Procedures Guide – Video

Deck Procedures Guide, First Edition
